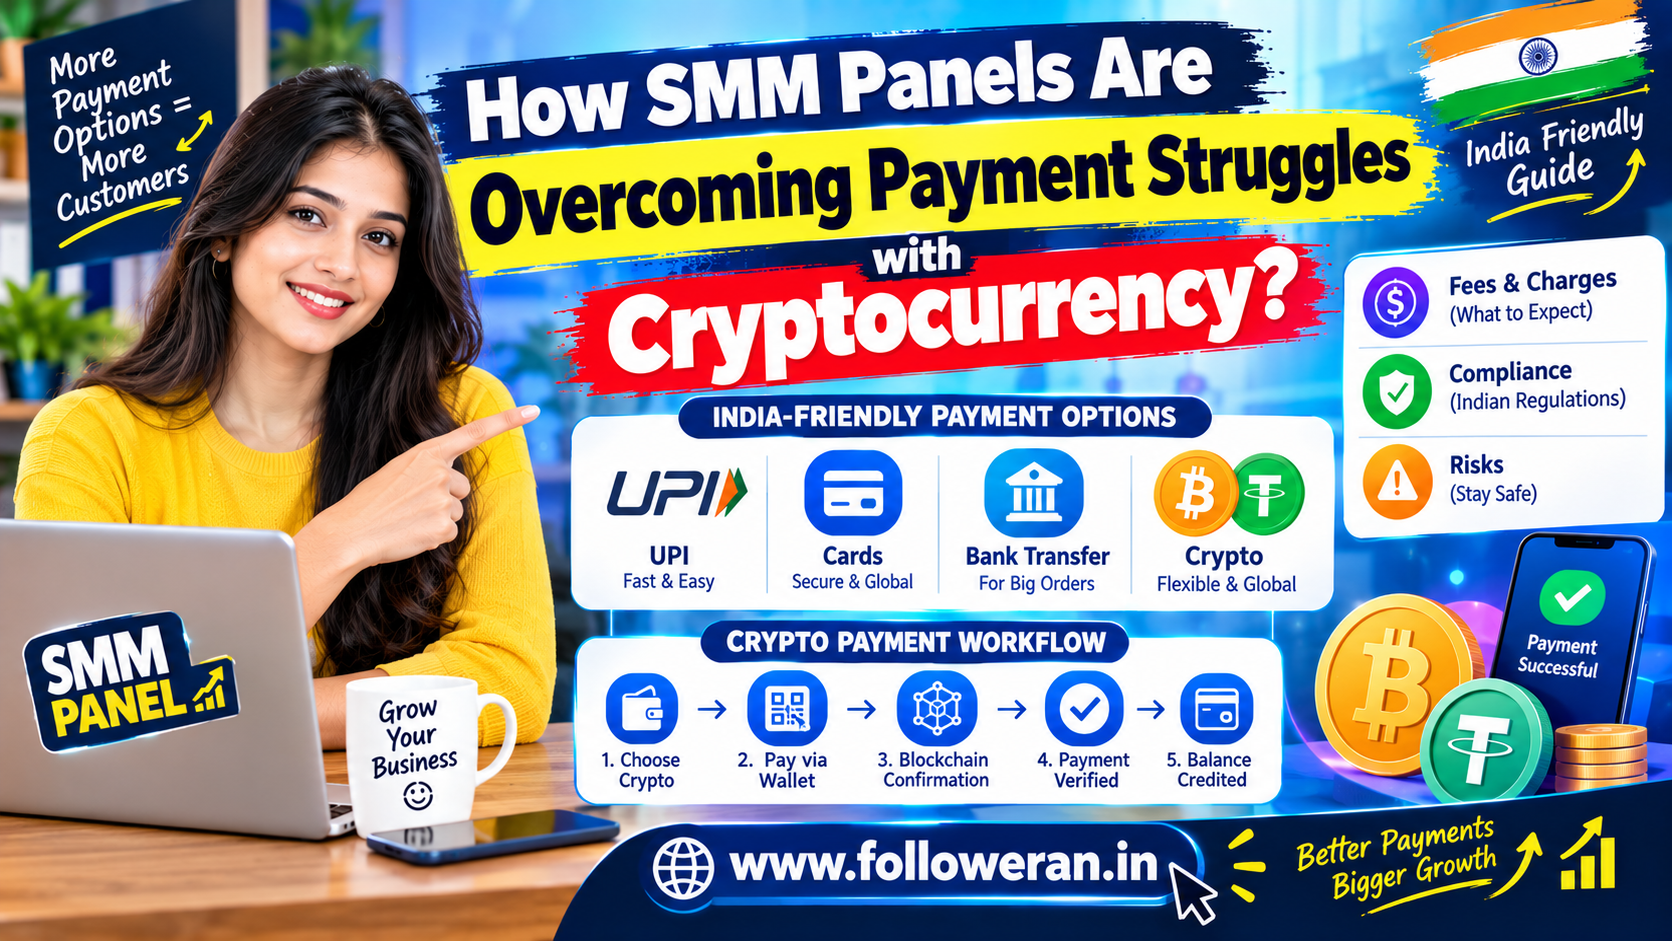
How SMM Panels Are Overcoming Payment Struggles with Cryptocurrency: India Guide
Payment processing can become a surprisingly important part of running an SMM panel in India.
A reseller may have excellent service pricing and a well-designed website, but if customers cannot conveniently add funds, the business can lose conversions. Payment failures, international cards, settlement delays, currency conversion and chargebacks can all create operational problems.
For Indian customers, traditional methods such as UPI, cards, net banking and bank transfers remain important. Cryptocurrency can be an additional payment option for customers who prefer digital assets or for businesses working with international customers.
However, crypto is not simply a cheaper replacement for UPI.
It introduces its own considerations, including network fees, exchange-rate volatility, wallet security, transaction monitoring, tax treatment and regulatory obligations.
India's current framework treats virtual digital assets (VDAs) as a regulated tax and AML subject in specific contexts. The Financial Intelligence Unit-India (FIU-IND) maintains AML/CFT guidance for VDA service providers, while the Income Tax Department continues to provide specific rules for VDA taxation and reporting.
For SMM panel owners, the right approach is therefore to treat cryptocurrency as one payment rail within a broader payment strategy.
Why Payment Methods Matter for an SMM Panel
An SMM reseller can receive customers from different countries and customer segments.
An Indian freelancer may want:
UPI
An international agency may prefer:
Card or PayPal
A crypto-native customer may prefer:
USDT, BTC or another supported asset
Therefore, offering several legitimate payment options can reduce friction.
A practical SMM payment stack might look like:
UPI + Cards + Bank Transfer + International Payment Option + Crypto
The exact combination depends on your customers, business structure and payment-provider availability.
Traditional Payment Options for Indian SMM Panels
Before adding cryptocurrency, understand the alternatives.
UPI
UPI is particularly convenient for Indian customers because payments can generally be made directly from a supported banking application.
For an India-focused panel, UPI can be an important payment option for:
Small deposits
Frequent reseller top-ups
Domestic customers
Agency accounts
Individual creators
Its main advantage is familiarity.
Cards
Debit and credit cards can make your panel accessible to customers who do not want to use UPI.
Cards can also be useful for international customers, depending on your payment provider and merchant category.
The main challenges can include:
Payment declines
Fraud screening
Chargebacks
Cross-border fees
Currency conversion
Net Banking and Bank Transfer
Bank transfers can be useful for larger deposits or business customers.
They can be particularly practical when an agency wants to add a substantial amount to its reseller balance.
The disadvantage is usually less automation compared with a real-time payment gateway.
International Wallets and Payment Services
Depending on your target customers and provider eligibility, an SMM business may support international payment solutions.
The important point is to verify whether your business category is accepted by the payment provider rather than assuming that any merchant can activate every payment method.
Where Does Cryptocurrency Fit?
Cryptocurrency can be useful as an additional payment method when the merchant and payment provider can legally and operationally support it.
Instead of sending money through a conventional card network, a customer can pay a crypto invoice or transfer supported digital assets to a designated payment address.
A simplified flow is:
Customer
↓
Selects Crypto
↓
Payment Invoice Generated
↓
Exchange Rate Locked
↓
Customer Pays
↓
Blockchain Confirmation
↓
Payment Provider Confirms
↓
Merchant Receives Settlement
This is much easier to manage when a payment processor handles invoice creation, exchange-rate management, monitoring and settlement.
Direct Wallet vs Crypto Payment Gateway
There are two broad models.
Model 1: Direct Wallet Payment
The panel displays a wallet address.
The customer sends cryptocurrency directly to that address.
Example:
USDT Wallet:
0x................
The merchant then monitors the blockchain and manually or automatically credits the customer's panel balance.
Model 2: Crypto Payment Gateway
A payment provider creates an invoice.
The customer receives:
Payment amount
Currency
Address or payment instructions
Expiration time
Payment status
The gateway monitors the transaction and tells your application whether the invoice is paid.
For a growing SMM panel, the second model can be easier to automate.
Recommended Crypto Payment Workflow
A robust workflow can look like this:
Customer
   ↓
Select Crypto Payment
   ↓
Your Server Creates Invoice
   ↓
Gateway Returns Invoice ID
   ↓
Customer Pays
   ↓
Blockchain Transaction Detected
   ↓
Required Confirmation(s)
   ↓
Gateway Marks Invoice Paid
   ↓
Webhook Sent to Your Server
   ↓
Verify Webhook
   ↓
Credit Customer Balance
   ↓
Create Transaction Record
The most important step is:
Do not credit the customer merely because the browser says “payment successful.”
Your backend should verify the payment status through a trusted server-side mechanism.
What Is a Crypto Invoice?
A crypto invoice is a payment request containing information such as:
{
  "invoice_id": "INV-582914",
  "currency": "USDT",
  "amount": "25.00",
  "status": "pending",
  "expires_at": "2026-09-09T18:30:00Z"
}
The payment gateway can later report:
{
  "invoice_id": "INV-582914",
  "status": "paid",
  "amount_received": "25.00"
}
Your application can then update the customer's wallet balance.
Why a Locked Exchange Rate Matters
Cryptocurrency prices can move quickly.
Suppose a customer needs to pay:
₹2,000
If your system calculates the BTC equivalent and leaves the invoice open for too long, the crypto value can change materially.
A gateway can instead calculate a payment amount and lock the rate for a limited period.
Some crypto processors explicitly use short-lived exchange-rate locks for invoices. BitPay, for example, says its invoice rates are honoured for up to 15 minutes.
This reduces confusion for both the customer and merchant.
Crypto Payment Fees
Crypto payments are not automatically fee-free.
There can be several different costs:
Payment processor fee
Blockchain network fee
Conversion fee
Settlement fee
Currency-exchange cost
Refund-related network cost
The exact combination depends on how you accept crypto.
For example, BitPay currently publishes merchant processing rates of 2% + $0.25 below $500,000 monthly transaction volume, dropping to 1.5% + $0.25 and 1% + $0.25 at higher published volume tiers; higher fees can apply to high-risk industries.
Another provider, CoinPayments, currently advertises a starting processing fee of 0.5% for coins and 1% for tokens, plus applicable network fees under its newer fee structure.
These examples demonstrate why an SMM-panel owner should compare the complete cost, not just the headline processor fee.
Example: ₹10,000 Crypto Payment
Imagine your customer needs to add:
₹10,000
Suppose the payment provider charges an illustrative:
1% processing fee
The processing cost would be:
₹10,000 × 1% = ₹100
The merchant would receive approximately:
₹9,900
before any additional network, conversion or settlement costs.
The actual amount can differ depending on the provider, currency, settlement method and applicable taxes.
Network Fees Are Different From Processor Fees
This distinction is important.
A payment provider might charge:
1% processing fee
while the blockchain itself may also require a network fee.
Those are two completely different costs.
Network fees vary by blockchain and network conditions.
CoinPayments currently states that blockchain network fees depend on the currency and network, and lists different fees for assets such as BTC, ETH, SOL, TRX and others.
Some payment processors may absorb, charge, or separately pass through certain network costs depending on their payment model.
Stablecoins Can Reduce Price Volatility
SMM panels may be interested in stablecoins because their intended value is linked to a reference currency such as the US dollar.
For example:
USDT
or
USDC
may make invoice pricing easier than accepting a highly volatile asset.
However, stablecoins are not risk-free.
You still need to consider:
Blockchain selection
Contract/network compatibility
Issuer and counterparty considerations
Wallet security
Regulatory treatment
Transaction monitoring
Settlement availability
Most importantly, never assume:
USDT = USDT on every network
A payment sent to the wrong network may be difficult or impossible to recover.
Network Selection Matters
Suppose your panel accepts:
USDT on TRON
but a customer sends:
USDT on Ethereum
Your receiving infrastructure may not automatically recognise the transaction.
Your checkout page should therefore clearly specify:
Asset + Network
For example:
USDT — TRON/TRC-20rather than simply:
USDTThis small detail can prevent expensive customer-support problems.
Crypto Payment Confirmation
A blockchain transaction being broadcast is not always the same as final payment confirmation.
The customer may see:
Transaction Sent
while your system sees:
Pending
A payment processor may require a specific number of confirmations before considering the invoice paid.
For example, BitPay currently requires six confirmations on BTC, BCH and DOGE and 50 blocks for ETH/ERC-20 tokens for certain merchant-payment completion flows.
The confirmation requirement is therefore provider- and network-specific.
Webhooks and Automation
For an SMM panel, manual verification of every crypto transaction is not practical.
A better solution is:
Crypto Gateway → Webhook → Your Backend → Verify → Credit Wallet
Example:
{
  "event": "invoice.paid",
  "invoice_id": "INV-582914",
  "status": "paid",
  "amount": "25.00"
}
Your backend should verify the event before crediting the customer.
Never Trust a Frontend Payment Status
This is a common security mistake.
Bad workflow:
Customer clicks “I Paid”
        ↓
Browser tells server “Paid”
        ↓
Balance credited
Better workflow:
Customer pays
        ↓
Gateway detects payment
        ↓
Gateway sends webhook
        ↓
Your backend verifies event
        ↓
Server confirms invoice
        ↓
Balance credited
The customer-facing browser should not be the authority for financial settlement.
Idempotency: Prevent Double Credit
Imagine the payment gateway sends the same webhook twice.
Without protection:
Webhook 1 → Add ₹1,000
Webhook 2 → Add ₹1,000 again
Customer receives:
₹2,000 balance
for a:
₹1,000 payment
Your backend should therefore store a unique invoice or transaction ID.
Example:
INV-582914 → processed = TRUEIf the same event arrives again, the server should recognise it and avoid crediting the account twice.
Build a Transaction Ledger
Every payment should create a permanent internal record.
For example:
| Field | Example |
|---|---|
| Transaction ID | TXN-92182 |
| Customer ID | 5041 |
| Invoice ID | INV-582914 |
| Currency | USDT |
| Network | TRC-20 |
| Amount | 25.00 |
| INR value | ₹2,100 |
| Processor fee | ₹21 |
| Status | Paid |
| Blockchain hash | 0x... |
| Created | 09 Sep 2026 |
| Confirmed | 09 Sep 2026 |
This makes reconciliation and accounting significantly easier.
Crypto Payments and INR Pricing
Your SMM panel can continue to display prices in INR.
For example:
Wallet recharge: ₹1,000
At checkout:
USDT equivalent: $X
Your payment processor can calculate the crypto equivalent based on the applicable exchange rate.
This means you can maintain:
INR accounting
while allowing:
Crypto settlement
where your payment infrastructure supports it.
Should an Indian SMM Panel Hold Cryptocurrency?
Not necessarily.
A merchant can use a payment processor that accepts cryptocurrency from the customer and settles the merchant in another supported currency.
This can reduce the need to manage cryptocurrency wallets directly.
For example, BitPay describes a merchant flow in which the customer pays a crypto invoice and the processor can convert the payment into a local settlement currency where supported.
However, whether a particular processor supports Indian merchants, Indian bank settlement, your business category and your desired currency must be checked before signing up.
Direct Crypto Holding vs Fiat Settlement
| Model | Advantage | Main Risk |
|---|---|---|
| Hold crypto | Exposure to digital assets | Price volatility |
| Instant conversion | Reduces volatility | Conversion costs |
| Processor settlement | Easier accounting | Provider dependency |
| Stablecoin holding | Lower intended volatility | Network/issuer/regulatory risks |
| Direct wallet | More control | Higher operational/security burden |
For a small reseller, avoiding unnecessary crypto custody may make operations easier.
India: Why Compliance Matters
Crypto payments in India require more care than simply adding a wallet address to your website.
India's regulatory framework includes specific AML obligations for businesses carrying out certain VDA-related activities. FIU-IND's current materials identify activities including exchange between VDAs and fiat currency, exchange between VDAs, transfer of VDAs, custody/administration and certain financial services related to VDA issuance as covered activities when carried out for or on behalf of another person in the course of business.
This does not mean every ordinary merchant accepting crypto for its own products or services automatically becomes a VDA service provider.
The exact legal classification depends on what your business actually does.
That is why an Indian SMM-panel owner should obtain professional advice before designing a business around crypto custody, exchange, transfer or conversion.
VDA Tax Rules in India
The Income Tax Department continues to state that income from the transfer of virtual digital assets is subject to a 30% tax plus applicable surcharge and 4% cess under Section 115BBH.
This should not be simplified into:
“Every crypto payment received by an SMM panel is taxed at 30%.”
The 30% provision concerns income from transfer of VDA, while an SMM panel's revenue from supplying services can involve different tax and accounting treatment.
The business should therefore separate:
Revenue from SMM services
from
Any gain/loss arising from VDA transactions
and have its accountant determine the correct treatment.
VDA TDS Rules
India's tax framework also contains TDS provisions relating to VDA transfers.
From 1 April 2026, VDA-related TDS provisions are represented under Section 393 of the Income Tax Act, 2025, and the Income Tax Department says the new Act largely retains existing TDS rates and thresholds.
For example, the new Form 141 includes a specific schedule for TDS on transfers of VDAs.
The exact responsibility and applicability can depend on who is transferring the VDA, the nature of the transaction and the parties involved.
For an SMM business, this is a CA/tax-law question, not something that should be guessed from a generic crypto-payment guide.
FIU-IND and AML Considerations
FIU-IND maintains AML/CFT guidance specifically for reporting entities providing services related to VDAs. The current guidance was updated on 8 January 2026.
If your business model moves beyond simply receiving consideration and begins facilitating VDA transfers, exchange, custody or related services for customers, regulatory obligations can become substantially more important.
Potential requirements can involve areas such as:
Customer identification
Transaction monitoring
Record keeping
Suspicious transaction reporting
Risk assessment
Compliance procedures
The precise obligations depend on the activities your business performs.
Do Not Treat Crypto as a Way Around Banking Restrictions
A common misconception is:
“If banks reject my business category, crypto solves the problem.”
That is not a reliable assumption.
Switching the payment rail does not automatically remove:
Tax obligations
AML obligations
Consumer-protection considerations
Platform restrictions
Business-registration requirements
Accounting obligations
Payment-provider terms
Crypto can change how money moves, but it does not automatically eliminate why the transaction exists or what legal obligations apply.
Chargebacks: An Advantage of Crypto, With a Trade-Off
One perceived advantage of crypto payments is that blockchain transactions generally do not operate like card chargebacks.
That can reduce a particular type of payment dispute.
But the trade-off is significant.
A blockchain payment may be difficult to reverse.
If the customer sends:
₹10,000 equivalent
to the wrong address or wrong network, recovering the funds may be impossible.
The merchant therefore needs much stronger checkout instructions.
Customer Protection Is Still Important
Your website should clearly show:
Payment amount
Crypto asset
Network
Exchange-rate expiry
Payment deadline
Refund rules
Minimum deposit
Confirmation requirements
Support contact
This reduces confusion.
Crypto Refunds Can Be Complicated
Suppose a customer pays:
$100 in BTC
and asks for a refund several days later.
The BTC value may now be:
$85
or:
$120
Which amount should the customer receive?
The answer depends on your published terms and applicable legal requirements.
Your refund policy should therefore define how crypto refunds are calculated.
Do not write:
“All crypto payments are non-refundable.”
without considering applicable consumer, contract and payment laws.
Instead, define:
Whether refunds are available
The valuation time
Refund currency
Network fee responsibility
Processing time
Wrong-network payments
Underpayments
Overpayments
Underpayment and Overpayment
Suppose your invoice requires:
25 USDT
but the customer pays:
24.50 USDT
Your system should not automatically credit the full amount.
Similarly, if they send:
30 USDT
your system should have a defined procedure for the extra amount.
Payment systems need explicit handling rules for:
Underpaid
Overpaid
Expired
Duplicate
Unsupported
Wrong network
BitPay's current merchant terms also distinguish unsupported payments and payment exceptions, illustrating why these edge cases should be addressed in payment operations.
Common Crypto Payment Risks for SMM Panels
Wrong network
A customer sends the correct asset on the wrong blockchain.
Wrong wallet
The customer sends funds to an incorrect address.
Volatility
The crypto value changes before settlement.
Security breach
A compromised wallet or API key can result in financial loss.
Regulatory changes
Rules can change.
Tax complexity
Crypto transactions can require additional accounting and reporting.
Provider dependency
A payment processor may change supported assets, countries or merchant categories.
Customer disputes
A customer may claim that the payment did not credit even though the blockchain shows a transaction.
Security Checklist for Crypto Payments
Treat the payment system like a financial application.
Use:
HTTPS
Server-side API keys
Webhook signature verification
Transaction IDs
Database constraints
Rate limiting
IP/network monitoring where appropriate
Admin two-factor authentication
Wallet security
Access logs
Backups
Never put private wallet keys or payment API secrets into frontend JavaScript.
Hot Wallet vs Cold Wallet
A hot wallet is connected to systems that actively process transactions.
A cold wallet is kept offline or otherwise isolated.
An SMM panel that automatically processes frequent customer payments may need some online infrastructure, but keeping large balances in an internet-connected wallet increases exposure.
A safer operational model can be:
Payment Processor → Automated Settlement → Controlled Business Account
rather than:
Website → Large Hot Wallet Balance
The exact architecture should reflect your transaction volume and security capability.
API Keys and Crypto Wallet Keys Are Different
Your payment processor API key allows software to interact with the payment system.
A wallet private key can control actual digital assets.
Compromising the second can be considerably more serious.
Do not store private keys in:
Public Git repositories
WordPress JavaScript
Browser local storage
Unencrypted configuration files
Shared spreadsheets
India-Friendly Payment Strategy
For an India-focused SMM panel, a sensible payment hierarchy could be:
Primary
UPI
Useful for the majority of domestic customers.
Secondary
Cards
Useful for users who prefer card payments and potentially international customers.
Business payments
Bank transfer
Useful for larger agency/reseller deposits.
International
Supported international payment method
Useful when your provider and business category allow it.
Optional
Crypto
Useful for customers who specifically prefer cryptocurrency and where your legal/payment infrastructure supports it.
This prevents the business from becoming dependent on one payment channel.
UPI vs Crypto
| Factor | UPI | Crypto |
|---|---|---|
| Indian customer familiarity | Very high | Lower |
| Settlement complexity | Relatively low | Higher |
| Price volatility | Low for INR transaction | Can be significant |
| Chargebacks | Payment-provider dependent | Generally different from card model |
| Blockchain fees | No | Yes |
| International use | Limited compared with global rails | Potentially broad |
| Tax/accounting complexity | Conventional | Higher |
| Wallet management | No | Potentially |
| Best use | Indian domestic customers | Optional domestic/international niche |
For most Indian customers, UPI is likely to remain the simpler payment experience.
Crypto should generally be considered an additional option, not a replacement for mainstream domestic payment methods.
Crypto vs Cards
| Factor | Cards | Crypto |
|---|---|---|
| Customer familiarity | High | Variable |
| Refund process | Established gateway process | More complicated |
| Chargebacks | Possible | Different model |
| Cross-border capability | Good | Potentially broad |
| Settlement speed | Depends on provider | Depends on blockchain/processor |
| Volatility | Low for fiat transaction | Potentially high |
| Compliance | Conventional payment framework | Additional VDA considerations |
| Setup | Gateway integration | Wallet/gateway integration |
There is no universal winner.
How an SMM Reseller Could Add Crypto Safely
A practical implementation might follow this sequence.
Step 1: Define the business requirement
Decide whether you need:
Crypto acceptance only
or:
Crypto acceptance + crypto custody
These are very different operational models.
Step 2: Select an appropriate payment provider
Check:
Country availability
Merchant onboarding
Supported business activities
Supported assets
Supported networks
Processor fees
Settlement currencies
KYC requirements
AML procedures
Refund process
Step 3: Create invoice support
Your backend should generate unique invoices.
Step 4: Add checkout instructions
Clearly identify asset and network.
Step 5: Implement webhook verification
Never trust client-side payment confirmation.
Step 6: Implement reconciliation
Every payment should map to one customer and one invoice.
Step 7: Test edge cases
Test:
Correct payment
Underpayment
Overpayment
Expired invoice
Wrong network
Duplicate webhook
Delayed confirmation
Failed API request
Step 8: Start with small transaction limits
Do not immediately expose large crypto deposits.
Step 9: Reconcile daily
Match:
Customer ledger
against
Payment processor
and, where relevant,
Blockchain records
Step 10: Review compliance regularly
Crypto rules, provider policies and tax procedures can change.
Example API Architecture
A developer can structure the payment integration like this:
                    CUSTOMER
                       |
                       v
                 YOUR WEBSITE
                       |
                       v
                 PAYMENT API
                       |
             +---------+---------+
             |                   |
             v                   v
        UPI / CARD          CRYPTO GATEWAY
             |                   |
             |                   v
             |               BLOCKCHAIN
             |                   |
             +---------+---------+
                       |
                       v
                 WEBHOOK / STATUS
                       |
                       v
                 YOUR BACKEND
                       |
              +--------+--------+
              |                 |
              v                 v
       TRANSACTION LEDGER   CUSTOMER WALLET
This architecture keeps payment processing separate from the customer-facing balance system.
Example Customer Wallet Logic
Suppose the customer has:
Current balance: ₹500
They make a crypto payment worth:
₹2,000
Your server verifies that the invoice is paid.
Then:
500 + 2,000 = ₹2,500The customer wallet becomes:
₹2,500
The transaction ledger records:
Credit: ₹2,000
Source: Crypto
Invoice: INV-582914
Status: Verified
This allows you to distinguish deposits from orders.
Do Not Credit Before Confirmation Rules Are Met
A common mistake is to credit a wallet immediately after seeing a blockchain transaction.
Depending on the asset, network and provider, you may need confirmation before considering the payment final.
The exact rule should come from the payment processor and blockchain risk model.
What About Crypto Discounts?
Some SMM panels may be tempted to advertise:
“5% discount for crypto payments.”
This can be a marketing tactic, but calculate the economics first.
Suppose:
Order = ₹10,000
Discount:
5% = ₹500
Payment processing:
₹100
The merchant effectively gives up:
₹600
before considering any network or conversion costs.
A discount only makes sense when the reduction in payment friction or processing cost genuinely offsets it.
Should SMM Panels Accept USDT?
USDT can be attractive because it is designed as a stablecoin, but the answer should depend on the provider, network and compliance setup.
Before supporting USDT, specify:
USDT + exact blockchain
and confirm that your processor supports that combination.
Never advertise “USDT accepted” without stating which networks are supported.
What About Bitcoin?
Bitcoin can be useful for customers who specifically prefer BTC.
However, transaction fees and confirmation times can change depending on network conditions.
Some processors also impose their own settlement or network-related costs.
Therefore, BTC can work as an option, but it should not necessarily be the only cryptocurrency you support.
What About Ethereum and Other Networks?
The same principle applies.
Every blockchain has its own:
Fee model
Confirmation behaviour
Transaction speed
Wallet requirements
Network risks
Your payment system should therefore be built around specific supported networks, not simply coin names.
How to Communicate Crypto Payments to Customers
Use simple instructions.
For example:
1. Choose Crypto Payment
2. Select USDT
3. Select the supported network
4. Pay the exact displayed amount
5. Wait for confirmation
6. Your panel balance will update after payment verification
Also warn:
“Do not send funds using an unsupported network.”
Crypto Payment FAQ
Can an SMM panel accept cryptocurrency in India?
An SMM panel may be able to offer cryptocurrency as a payment method through an appropriate payment provider, but legal, tax, AML and merchant-onboarding considerations depend on the business model and activities involved.
Is crypto better than UPI for Indian customers?
Not generally. UPI is more familiar for domestic Indian payments. Crypto can serve as an additional option for customers who specifically want to pay with digital assets.
What are crypto payment fees?
Fees vary by processor, network and asset. Current published merchant examples include processor rates ranging from around 0.5% at some providers to around 1–2% plus a fixed component at others, with network costs potentially added separately.
Does cryptocurrency have network fees?
Yes. Blockchain transactions generally have network costs, although how those costs are presented to the merchant or customer depends on the payment method and processor.
Can I receive USDT for SMM services?
Technically, a payment system may support USDT, but you must verify the supported network, processor availability, merchant eligibility and applicable Indian legal/tax requirements before enabling it.
Do I need a crypto wallet?
Not necessarily. A payment processor can sometimes accept crypto from customers and handle conversion or settlement, reducing the need for the merchant to directly manage crypto assets.
Is crypto income taxed at 30% in India?
India's Income Tax Department states that income from the transfer of VDAs is subject to a 30% tax plus applicable surcharge and cess under the relevant VDA tax provisions. This should not be interpreted as saying that every rupee of an SMM business's service revenue received in crypto is automatically taxed at 30%; the exact tax treatment depends on the transaction structure.
Are crypto payments anonymous in India?
You should not design a merchant system around an assumption of anonymity. Depending on the payment method and provider, transactions can involve customer identification, transaction monitoring and record-keeping requirements.
Does accepting crypto make an SMM business a VDA service provider?
Not automatically. FIU-IND's VDA framework covers specified activities such as exchange, transfer and custody when performed for or on behalf of another person in the course of business. Whether a particular SMM merchant falls within those activities depends on what it actually does.
Should I accept crypto directly into my personal wallet?
For a business, using a proper merchant/payment setup is generally easier to reconcile and control than mixing customer payments with a personal wallet. The appropriate structure depends on your business and compliance requirements.
Final Thoughts
Cryptocurrency can help an SMM panel diversify its payment options, particularly when serving international customers or users who prefer digital assets.
But cryptocurrency should not be marketed as a magic solution to payment problems.
For an India-focused SMM business, a practical payment strategy is usually:
UPI for domestic convenience
Cards for broader payment access
Bank transfer for larger business deposits
Crypto as an additional option
The biggest advantage of crypto is payment flexibility. The biggest disadvantages are regulatory complexity, transaction irreversibility, network fees, security responsibilities and accounting complexity.
A professional SMM panel should therefore build crypto payments around a proper invoice system, exact asset/network selection, server-side payment verification, webhook security, transaction reconciliation and clear refund rules.
Most importantly, separate crypto payment acceptance from crypto exchange, custody or transfer services. Those activities can create very different regulatory obligations in India.
Before launching cryptocurrency payments commercially, have your payment flow reviewed by an Indian CA and appropriately qualified legal/compliance professional, especially if your business will hold, convert, transfer or otherwise facilitate VDAs for customers.
